
In the current automotive landscape, deal flow is no longer a given: it is an engineered outcome. As we move through 2026, the industry is facing a unique set of pressures: a massive surge in off-lease returns, stabilized but lower residuals, and a tightening of per-unit margins that demands a more sophisticated approach to the F&I office. For dealership owners and managers, the traditional “business as usual” approach to financing is a recipe for stagnation.
Maximizing your front-end gross and increasing your turn requires more than just having “a leasing option.” It requires a strategic integration of car dealership lease programs that remove friction from the desking process and provide customers with the monthly payment flexibility they now demand.
Here are 10 things you need to know about modern lease programs to keep your inventory moving and your profitability climbing.
1. Velocity is the new volume
The reality is that a deal delayed is often a deal lost. In a high-volume environment, operational friction is the silent killer of profitability. According to Cox Automotive forecasts cited by WardsAuto, approximately 3 million total lease maturities are expected in 2026, straining BDC and F&I departments that rely on manual processes.
If your current financing partner takes hours: or days: to provide a callback, you are leaking deals to the competition. Modern auto dealer financing solutions, like those provided by AmeriTrust Financial, leverage instant decisioning to return multiple callbacks in seconds. When you can present options while the customer is still in the chair, your closing ratio shifts fundamentally.
2. The affordability advantage
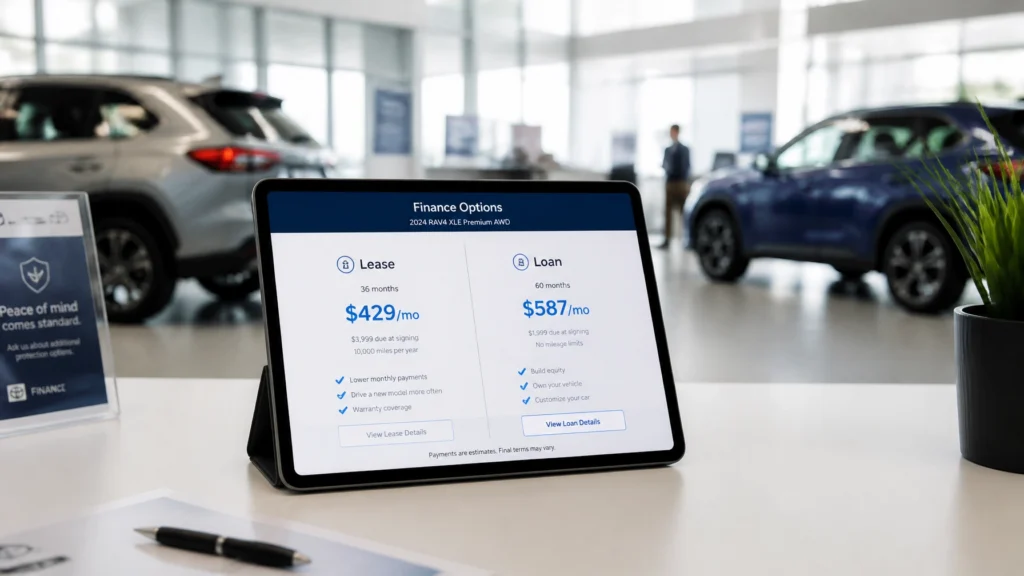
Affordability is the primary hurdle in the 2026 market. With vehicle prices remaining at historic highs, the gap between a monthly loan payment and a lease payment has widened significantly. According to LendingTree, citing Experian Q1 2026 data, the average new-vehicle loan payment is $770 per month while the average new-vehicle lease payment is $619 per month, a gap of $151 per month.
Strategic dealers lead with this gap. By utilizing a Free Live Inventory Lease Calculator, you can show customers side-by-side comparisons of lease vs. loan payments in real-time. This transparency doesn’t just build trust; it moves units that would otherwise be out of the customer’s monthly budget.
3. Used car leasing is your best margin protector
As per-unit gross on traditional used car retail continues to compress, used vehicle leasing emerges as a vital margin protector. Used car lease programs allow you to move 3- to 5-year-old inventory with the same monthly payment appeal as new cars.
The catch is that many dealers avoid used leasing because they perceive it as complex or risky. However, with stabilized residual curves, used leasing offers a predictable way to move inventory while maintaining strong F&I penetration. It allows you to create a “nearly-new” tier of inventory that appeals to value-oriented shoppers.

4. Preparing for the 2026 EV wave
Industry data points to a sharp rise in EV lease returns heading into 2026. According to CDK Global, more than 300,000 EVs are projected to return from lease in 2026, versus roughly 123,000 in 2025. This influx presents a significant remarketing risk due to fluctuating EV residuals. If you aren’t partnered with dealer financing companies that understand how to value and lease these units, you’ll find yourself with a lot of “dead” inventory on the lot.
Successful dealers are using flexible leasing structures to move these EVs, often extending terms or using manufacturer-subsidized programs to keep the payments aggressive. Managing the battery health and residual risk through a specialized partner is the only way to navigate this wave without eroding your bottom line.
5. Automated contract logic removes “Desking Drama”
Friction often starts at the desk. Manual data entry leads to errors, and errors lead to re-contracting: a process that kills customer satisfaction and delays funding. Automated contract processing is no longer a luxury; it is a necessity for maintaining deal flow.
Our technology integrates directly with Route One and Dealer Track to convert applications into leases and pre-fill customer contracts automatically. If you can eliminate the manual “back-and-forth” between the sales desk and the F&I office, you increase the speed of every transaction.
6. Capturing the subprime “One Pay” market
In a high-interest-rate environment, subprime and near-prime customers are often squeezed out of traditional financing. However, these customers represent a significant portion of the market that many dealers overlook.
The introduction of “One Pay” lease options for both subprime and prime customers provides a strategic “out” for these deals. By allowing a single upfront payment, you remove the monthly payment risk for the lender and provide the customer with a viable path to a late-model vehicle. This is how you save deals that other dealerships are turning away.
7. Inventory visibility as a sales tool
If your lease payments aren’t advertised on your website, you are invisible to the modern shopper. Customers in 2026 are payment-shoppers first. They aren’t looking for a “sticker price”; they are looking for a monthly commitment.
Top-performing dealerships use automated inventory feeds that update every night. This ensures that every vehicle on your site has an accurate, live lease payment attached to it. When your digital showroom matches the reality of your F&I office, the transition from “click” to “close” becomes seamless.

8. The “Freedom Lease” strategy
The standard 36-month lease doesn’t fit every customer’s lifestyle. To truly optimize deal flow, you need a product that offers more flexibility. The Freedom Lease provides flexible end-of-term options, allowing the customer to adapt to their changing needs.
For the dealer, this flexibility is a powerful closing tool. It allows you to offer a “safety net” to customers who are hesitant to commit to a long-term contract in an uncertain economy. Positioning yourself as a provider of flexible solutions: rather than just another lender: is how you build long-term loyalty.
9. The necessity of floor training
Even the best lease program will fail if your sales floor doesn’t know how to present it. Many sales professionals are comfortable talking about price but stumble when explaining the nuances of a lease. This internal friction can cause a customer to lose confidence.
At AmeriTrust Financial, we believe that free lease training is as important as the funding itself. We host Q&A sessions and provide resources to ensure your team can explain money factors, residuals, and the benefits of leasing with total confidence. When your team speaks with authority, the customer buys with confidence.
10. Liquidity depends on rapid funding
At the end of the day, your dealership runs on cash. A deal isn’t truly done until the funds are in your account. “Rapid Funding” isn’t just a marketing slogan; it’s a vital component of your business’s liquidity.
Most contracts processed through our automated systems are funded the same day. This speed allows you to turn your capital faster and acquire more inventory without being held back by “pending” deals. If your current financing partner is sitting on your money for days, they are actively hindering your growth.

Summary and Key Takeaways
Navigating the 2026 automotive market requires a shift from passive lending to active, strategic lease management. To improve your deal flow and protect your margins, keep these takeaways in mind:
- Prioritize Speed: Use automated decisioning to catch the customer while they are still on-site.
- Focus on Payments: Leverage the $151/month gap between leases and loans to close more deals.
- Expand Your Inventory: Don’t ignore used leasing; it’s a powerful tool for moving 3- to 5-year-old units.
- Automate Everything: Eliminate manual contract errors to speed up funding and reduce re-contracting.
- Invest in Training: Ensure your sales team is as confident in presenting a lease as they are a traditional sale.
The reality is that the dealerships that win in 2026 will be the ones that remove the most friction from the buying process.
Ready to Streamline Your Deal Flow?
Stop letting complex desking and slow funding hold back your profitability. Partner with a finance company that has “sat where you sit” and understands the daily grind of the dealership floor.
Contact AmeriTrust Financial today to see how our automated leasing solutions and rapid funding can transform your F&I office.
AmeriTrust Financial Technologies Inc. is an Equal Opportunity Lender. NMLS ID 2708412. AmeriTrust maintains a fair lending monitoring program to help ensure that credit decisions and product placements across all credit tiers are made on the basis of creditworthiness and program eligibility, not characteristics protected under applicable fair lending laws. Lease and finance product descriptions, figures and payment comparisons in this article are general and illustrative only and are not an offer of credit or a lease. Actual products, terms, payments, and availability vary based on approved credit, program eligibility, vehicle, and applicable fees. Not all customers will qualify for every product or structure described.
